Clean the slate.
You get one simple term loan at a set interest rate. It pays off your current credit card balances, all at once. One loan, one payment, no games.
Our specialty
Most business owners think funding means one big loan. There's another way, and almost nobody takes the time to explain it. It's called credit card stacking, and it works in three steps.
You get one simple term loan at a set interest rate. It pays off your current credit card balances, all at once. One loan, one payment, no games.
Once those payoffs show up on your credit report, your profile changes. Lenders see you differently. This window is the part most people miss. Apply too early and you get denied. Wait too long and you lose the advantage.
At just the right time, our team applies with several lenders at once. Some cards may be in your name, some in your business's name, whatever fits your situation. Many come with 0% interest for the intro period. That's your working capital, and it costs you nothing in interest while you put it to work.
Every lender is different. One funder might not even look at your credit score while another one will. We can apply with two funders at the same time and see what each comes back with, so you get options, not a single yes-or-no.
You're not getting one person squeezing your file in between calls. Here's who's actually working it.
Your file gets more than one set of eyes before it goes to a lender.
Funding files are what this team does — not something squeezed in between other work.
You still deal with Deb. She just has 25+ years of accounting experience overseeing every file behind her.
Before any lender says yes, they look for the same handful of things. Check yourself against this list and you'll know exactly where you stand.
Have most of these? You're closer than you think. Missing a few? Every one of them is fixable, and helping people fix them, in the right order, at the right time, is exactly what we do.
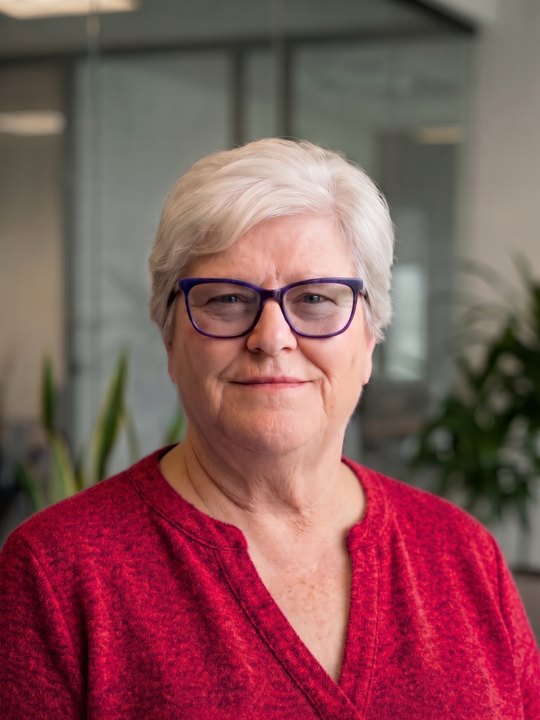
“A lot of people say no to funding companies for one reason: they don't know who to trust. So we made trust the whole point.”Deb Hellman, Founder & Funding Advisor
Answer a few questions and see where you stand. Soft pull only, no pressure either way.